TH!NCK AUTOMOTIVE Architecture concept
HomeTH!NCK AUTOMOTIVE

Market reality

IN FOCUS

Market shifts translated into operations. Not only what is changing in automotive and mobility, but what it means for performance and execution.

02 · Market reality

Better performance today. A changing business tomorrow.

Consolidation, margin pressure, electrification, new distribution models, changing customer behaviour, technology and an increasingly tight labour market are putting business and revenue models and organisations under pressure at the same time.

At the same time, organisations must invest in tomorrow's business. The capacity to change tomorrow must be earned today — through performance, profit and cash flow.

Future readiness is not about predicting change, but about being able to perform repeatedly as circumstances evolve.

PROFITABILITYmargins · costs · cash flow

With thin margins, small differences in conversion, gross margin, cross-selling and upselling, used-vehicle performance, workshop productivity, parts, personnel costs and working capital have a disproportionate impact on profitability.

CONSOLIDATIONscale · integration · synergies

Larger dealer groups and acquisitions create potential. Value emerges only when economies of scale, standardisation, synergies and integration translate into better operational performance.

CUSTOMERbehaviour · relationships · customer value

The customer journey is changing across research, purchase, finance, servicing and loyalty. This affects both Sales and Aftersales, conversion, retention, customer relationships and lifetime value.

VALUE CHAIN & DISTRIBUTIONOEM · importer · retail

Roles and responsibilities across OEMs, importers or National Sales Companies and retail networks are shifting. This affects pricing, inventory, data, customer relationships, Sales, Aftersales and commercial execution.

MARKET & COMPETITIONbrands · portfolio · pricing

New entrants, changing brand positions and different pricing and product strategies are putting pressure on portfolios, commercial performance, network strategy and differentiation.

TECHNOLOGYdigitalisation · data · AI

Technology is changing customer interaction, commercial management, processes, decision-making and productivity — from lead management and conversion to scheduling, workshops and management information.

PEOPLE & ORGANISATIONtalent · leadership · capabilities

New technologies and business models require different skills, while both technical and commercial talent remain scarce. The challenge is therefore shifting from headcount alone towards productivity, leadership and capability development.

BUSINESS MODELelectrification · mobility · revenue economics

Electrification and new mobility models are changing the economic mix across new and used vehicles, cross-selling and upselling, accessories, parts, workshops, energy, leasing and other mobility services.

The market is not changing along a single dimension. Several forces are reshaping the same business system simultaneously. It is precisely their interaction that creates new performance gaps and transformation challenges.
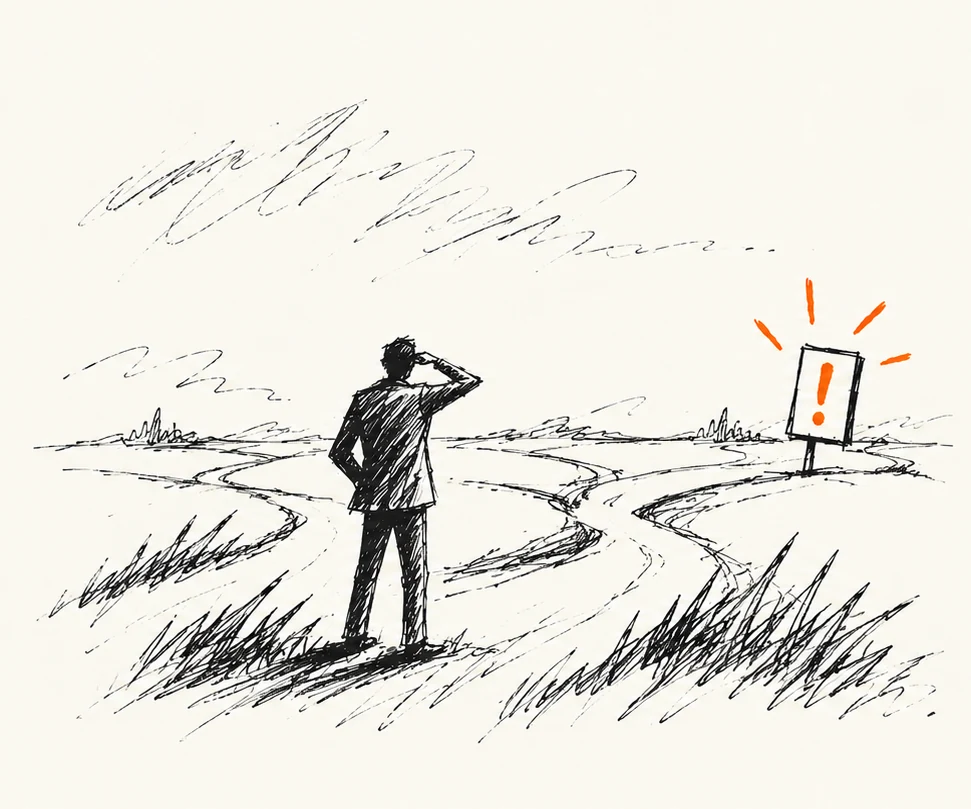
Ruwe TH!NCK-schets: een manager tussen uiteenlopende marktkrachten en keuzerichtingen
The challenge is to understand how market developments, the organisation and leadership influence each other — and where targeted choices can make the difference.
The pressure is coming from multiple directions.
What lies beneath the surface?Read the context

The combined impact of margin pressure, consolidation, electrification and changing distribution models makes clear decisions on profitability, capacity and investment increasingly important.

The central leadership challenge is to create room for necessary change without undermining today's performance.

The management question is not whether change is needed, but where performance and future readiness intersect, and which decisions will make the greatest difference now.

MARKET REALITY IN NUMBERS

Six signals that make the performance and transformation challenge tangible.

Profitability under pressure

1,12%

Revenue growth alone is not a profitability strategy.

Evidence

BOVAG reported average profitability of 1.12% per dealership in H1 2026, alongside 4.5% revenue growth. Profitability recovered compared with H1 2025, but margins remain narrow.

BOVAG · Branche Barometer · H1 2026 ↗

Aftersales & productivity

−6.7%

Higher revenue does not automatically mean higher productivity.

Evidence

Billed hours per technician FTE fell from 1,424 to 1,328 in 2025 (−6.7%), while labour costs increased. A concrete signal about workshop productivity, capacity and operational management.

BOVAG · Branche Barometer · 2025 ↗

Commercial performance

−3.5%

Commercial effectiveness is becoming increasingly important.

Evidence

In H1 2026, new-vehicle sales volumes were 3.5% lower than in H1 2025. New-vehicle revenue nevertheless increased by 1.8% due to higher average selling prices. Conversion, sales mix and value per transaction require attention.

BOVAG · Branche Barometer · H1 2026 ↗

Customer data & technology

26%

Available data does not equal realised commercial potential.

Evidence

Only 26% of respondents to CitNOW's research among automotive retail decision-makers in the UK and Europe said they derive excellent value from customer data. This is not a Netherlands-specific figure.

CitNOW · Time to Shift Gears · 2025 ↗

Leadership & capacity

57.7%

Performance also depends on people and execution capability.

Evidence

In the February 2026 BOVAG Business Monitor, 57.7% of respondents identified rising personnel costs as a challenge and 38.2% cited staff shortages. The survey covers BOVAG businesses, not exclusively car dealers.

BOVAG · Ondernemersmonitor · februari 2026 ↗
What other market signals reinforce this picture?

Effective transformation

15%

belongs to the group that effectively orchestrates transformation across several interconnected domains.

KPMG · 2025 ↗

Vehicle fleet electrification

3.7%

of Europe’s passenger car fleet was externally chargeable in 2024 — relevant to the installed base, aftersales and capabilities.

ACEA · Vehicles on European Roads 2026 ↗

The same market forces affect every organisation differently. They become relevant when market change translates into a performance, organisational or economic value challenge.

See where market change becomes a performance challenge →
A first conversation

Start with the challenge.

Where do results fall short? What improvement is achievable? And what is needed to realise it?

Discuss your challenge
Dave Kessels · Managing Partnerdave@thinckautomotive.nl+31 6 83 01 29 97